A reverse mortgage guide for families
Good information can make a family conversation easier.
When someone you care about is considering how home equity fits into a future plan, a calm conversation can begin with clear questions. This HECM-focused guide is designed to help families understand the topic together—while the homeowner remains the decision-maker.
General education only. Not a commitment to lend or a promise of loan approval.
Talk through your questions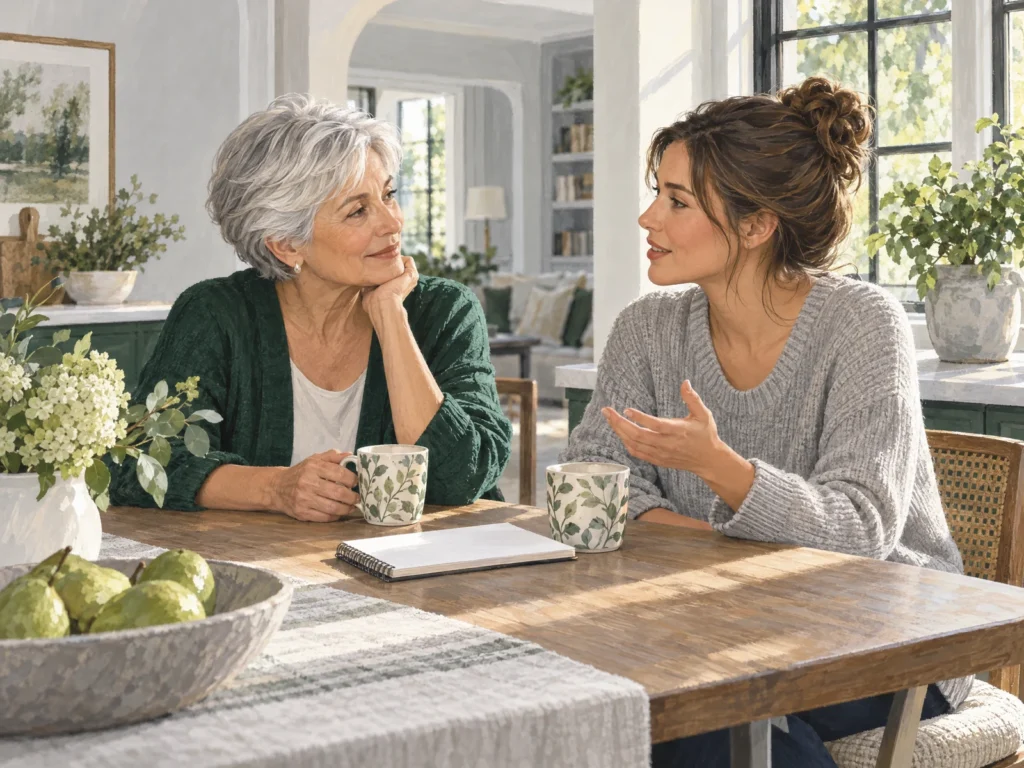
Pat and Alex start with questions, not assumptions.
Pat, a homeowner, invites her adult daughter Alex to help gather information before deciding whether a reverse mortgage belongs in Pat’s plan. Alex asks about costs, responsibilities, alternatives, and what may happen later.
Pat decides which questions matter and whether to speak with a lender, a HUD-approved counseling agency, or another adviser. Family involvement can support the conversation without replacing the homeowner’s choices.
What a reverse mortgage is—and is not
All information here is focused on Home Equity Conversion Mortgages (HECMs). HECMs are for homeowners age 62 or older, and financial and property criteria apply.
A loan secured by the home
A HECM is a loan that uses the home as security. The homeowner keeps title to the home; it is not a sale or a transfer of ownership.
No monthly mortgage payment does not mean no cost
Interest and fees are added to the loan balance over time. The balance can grow and the homeowner’s equity can decrease.
Requirements continue
Property taxes, homeowners insurance, home upkeep, and principal-residence requirements continue. Not meeting loan requirements can create foreclosure risk.
Questions a family can ask—without deciding for the homeowner
A HECM may provide a way for a qualifying homeowner to access a portion of home equity, and it also brings costs, trade-offs, and ongoing responsibilities. These questions can help a family consider both sides.
Costs now and later
What upfront and ongoing costs apply? How could interest and fees affect the loan balance and the equity that may remain?
Responsibilities at home
How will property taxes, homeowners insurance, upkeep, and principal-residence requirements be handled over time?
Alternatives and timing
What other options should be considered, including other financing approaches, selling, or using other resources?
Spouse and household
How could a spouse or other people living in the home be affected? An eligible non-borrowing spouse may have conditional protections; a counselor can explain how rules may apply.
What happens later
If the loan becomes due and payable, what repayment options could the homeowner or heirs have? Families may want legal or estate-planning guidance as appropriate.
Independent counseling
Before a HECM can be obtained, counseling from a HUD-approved reverse-mortgage counseling agency is required. The counselor can discuss loan mechanics, responsibilities, and alternatives.
Meet Linda Williamson
Your local point of contact
Branch Manager, NMLS #269744. Licensed in Wisconsin.
Questions families often bring to the table
These answers are general education and are shown in full so the questions are easy to review together.
Does a reverse mortgage mean the homeowner gives up title?
No. With a reverse mortgage, the homeowner retains title while the loan is secured by the home.
Are there monthly mortgage payments?
HECM borrowers generally do not make monthly mortgage payments, but interest and fees are added to the balance. Taxes, insurance, upkeep, and occupancy requirements remain.
Is counseling required?
Yes. Independent counseling from a HUD-approved reverse-mortgage counseling agency is required before a HECM can be obtained. A counselor can discuss costs, responsibilities, and alternatives.
What happens to heirs?
What happens depends on coborrowers, any eligible non-borrowing spouse, loan terms, and circumstances. When a loan becomes due and payable, heirs may need to consider repayment options and seek legal or other advice as appropriate.
Can family members make the decision?
Family members can help gather information and prepare questions. The homeowner decides whether a reverse mortgage fits their own plan.
Bring your questions to the conversation.
Talk through general HECM questions and identify points to bring to independent HUD-approved counseling.
Talk through your questionsOr email linda.williamson@fairwaymc.com
Let's Connect!